Insight

Walking Drivers: A “Sudden” Defense to Rear-end Liability

Published on: August 2, 2016
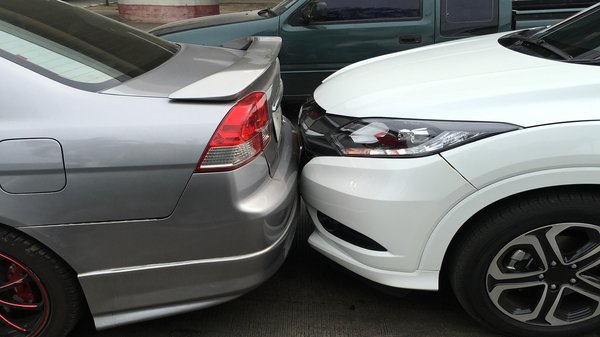
A rear-end collision is a unique animal in the law. Plaintiff’s attorneys seek them out, and insurance companies fear them­­--sometimes for good reason. The "rear-end" accident is unique because proof of the mere fact that one vehicle strikes the rear of another creates a strong legal presumption of fault under La. R.S. 32:81. While this presumption is formidable, it may be overcome.

The rear-end presumption is premised upon the duty to not follow too closely and the law will assume that the following driver breached this duty when there is impact. However, the following driver can escape liability if he shows that his vehicle was under control, that he followed at a safe distance, and that the lead driver negligently created a hazard which could not have reasonably been avoided. For instance, if it is shown that the reckless or unpredictable driving of the lead motorist created a sudden emergency, the following driver will not be at fault. Brewer v. J.B. Hunt Transport, Inc., 35 So.3d 230 (La. 2010). Once established, the sudden emergency defense trumps the “rear-end presumption.”A "sudden emergency" is created when a driver is placed in a position of imminent peril that he or she did not create through their own conduct. Hickman v. Southern Pacific Transport Company, 262 So.2d 385 (La. 1972). When a driver can demonstrate the existence of a sudden emergency, they are not negligent for failing to do what a reasonable person might have done to avoid the accident had they been given enough time to assess and react to the situation.In Jewitt v. Alvarez, 179 So.3d 645 (La. App. 2 Cir. 9/30/15), a following driver who rear-ended the vehicle of the lead driver was free from fault as a result of the sudden emergency defense where the facts revealed that the accident was solely caused by the slow speed of the lead driver (who almost came to a complete stop on the interstate) and the presence of surrounding traffic prevented the following vehicle from taking evasive action.In Carias v. Loren, 2015 WL 1019481 (La.App. 1 Cir. 3/9/15), an eighteen-wheeler was traveling in the middle lane of the interstate when a "phantom driver" moved without warning from the left lane to the middle lane and slammed on its brakes in front of the eighteen-wheeler. In attempt to avoid the collision, the driver of the eighteen-wheeler swerved to his right and impacted a vehicle which then struck the plaintiff's vehicle. The driver of the eighteen-wheeler invoked the sudden emergency defense; the court agreed and found the defendant-driver free from fault.Rear-end collisions are hard to defend, but a defendant may want to gather a clear understanding of all of the facts before accepting liability. If these facts support the sudden emergency defense, the driver may "walk."

Posted by:

Disclaimer

Keogh Cox & Wilson, Ltd. provides this blog as a public service for general information only. The materials contained herein may not reflect the most current legal developments or even express the opinion of all or even most of Keogh Cox attorneys. Such material does not constitute legal advice or form any attorney-client relationship. Keogh Cox and all contributing author(s) expressly disclaim all liability to any person with respect to the contents of this Web site and Blog and expect that no reliance will be made upon the information provided.
Continue Reading

Explore legal perspectives on the issues shaping Louisiana's key industries and courtrooms.

Insight

Louisiana Supreme Court Finds Business Interruption Coverage Does Not Apply to Losses Attributable to COVID-19

The COVID-19 pandemic had a profound impact on the global economy. Louisiana was not spared, and many businesses had to close as sales to their customers slowed or stopped altogether. Not surprisingly, the question arose regarding whether business interruption insurance would provide coverage to businesses in this situation. The Louisiana Supreme Court recently was asked this question in Cajun Conti, LLC v. Certain Underwriters at Lloyd’s, London and found that the policy at issue did not provide such coverage.

The mayor of New Orleans issued a proclamation on March 16, 2020, that prohibited most public and private gatherings. This applied to restaurants, whose business initially was limited to takeout and delivery services. Before the pandemic, Oceana Grill, a restaurant located in the French Quarter, could serve up to 500 customers at one time. However, it had to limit its business to takeout and delivery services when the mayor’s proclamation was announced. Because of social distancing guidelines, it remained at 60% or less capacity throughout the pandemic.

Oceana maintained a commercial insurance policy with loss of business income coverage and filed suit to request a declaratory judgment that the “policy provides business income coverage from the contamination of the insured premises by COVID-19.” Oceana’s insurer argued that there was no coverage under the policy because COVID-19 did not cause “direct physical loss of or damage to property” under the policy’s terms.

The trial court denied Oceana’s request for declaratory relief at trial. The appellate court reversed and found the policy’s terms ambiguous because it held “direct physical loss” could mean loss of use of the property. Because the pandemic prevented the full use of the property due to capacity limitations, the appellate court found coverage was triggered.

The Supreme Court disagreed and reversed the appellate court’s decision, finding its focus on the use of the property to be misguided. The Court found that suspension of operations “caused by direct physical loss of or damage to property,” as defined by the policy, required “the insured’s property to sustain a physical, meaning tangible or corporeal, loss or damage.” The Court noted that the restaurant’s physical structure was not lost or damaged because of the pandemic. COVID-19 restrictions did not cause damage or loss that was physical in nature. Therefore, the policy did not provide coverage for loss of business income.

Whether a policy affords coverage depends on the terms and conditions of each policy and the facts of each case. However, in light of this decision, businesses with insurance policies that include provisions with language like that at issue in Cajun Conti should not anticipate coverage for loss of business income allegedly caused by the COVID-19 pandemic.

Case References:

Cajun Conti LLC v. Certain Underwriters at Lloyd's, London, 2022-01349 (La. 3/17/23), 2023 WL 2549132.

Insight

“Collectibility” in Legal Malpractice: Can a client have greater rights against an attorney that existed in the underlying case?

It is well-established that a client in legal malpractice shall have no greater rights against their attorney than they had against the original defendant. That is, until the recent decision by the Supreme Court in Ewing v. Westport Insurance Corporation, 20-00339 (LA. 11/19/20), 2020 WL 6789490 where the Louisiana Supreme Court held that the “collectibility“ of the underlying judgment against the defendant is neither part of the plaintiff’s burden of proof nor the proper subject of an affirmative defense.

In Ewing, the defendant/attorney fax-filed a petition for damages but failed to forward the original petition within seven days as required by statute. As a result, the claim he sought to advance on behalf of Elaine Ewing prescribed. Ewing sued her attorney and his insurer.

Prior to trial, the tortfeasor testified that he would have filed for bankruptcy had an excess judgment been entered. On this basis, the defendants obtained a motion for summary judgment establishing that the underlying tortfeasor would have been unable to pay any amount above the $30,000 in available insurance coverage. Following trial, an award of $30,000 was entered in favor of the plaintiff and the plaintiff appealed.

The appellate court reversed citing to the decision in Rodriguez v. Traylor, 468 So.2d 1186, 1188 (La. 1985) which held that “the wealth or poverty of a party to a lawsuit is not a proper consideration in the determination of compensatory damages.“

The Supreme Court upheld the appellate opinion. In the analysis, Chief Justice Johnson on behalf of the majority also cited to the Rodriguez decision for the proposition that the wealth of the tortfeasor is not relevant to damages. The majority acknowledged that a majority of courts nationwide hold that the collectibility of a judgment is an essential element of a plaintiff’s legal malpractice case. It also observed “a growing trend” in other states to allow the defendant/attorney to plead collectability as an affirmative defense. Nevertheless, the Supreme Court in Ewing chose to follow neither position.

The defendants in Ewing did not argue that collectibility was part of the plaintiff’s burden. However, they did assert an affirmative defense on this basis. In rejecting this defense, the Ewing court found that nothing in statutory law of Louisiana limits damages based upon the collectibility of a judgment against a particular tortfeasor. In Ewing, it was established that the tortfeasor would have been immediately unable to pay an excess judgment. Nevertheless, the majority highlighted that a money judgment is valid for 10 years and may be revived for successive 10-year periods. As such, the court concluded that the money judgment has intrinsic value, regardless of immediate collectibility. To quote the majority, “impecunity is a snapshot in time.”

The concurring opinion by Justice Weimer reasons that there may be certain and rare cases where the underlying tortfeasor is truly judgment proof. In that circumstance, he writes that summary judgment in favor of the defendant may be appropriate but not under the record before the court.

Writing for the dissent, Justice Crain observed: “Thirty states have determined collectibility is relevant in a legal malpractice action. No state has reached a contrary conclusion, until now.” According to the majority, the absence of any statute making collectability a relevant consideration mandated the result under our civilian traditions. Justice Crain disagreed and argued that the majority opinion is inconsistent with the Code of Evidence articles which generally allow the admissibility of relevant evidence such as an inability to pay. La. L.C.E. art. 402. In support of his position, Justice Crain gave a hypothetical scenario involving an insolvent, uninsured driver who rear-ends a world-class professional athlete rendering him a paraplegic, resulting in damages and $50 million. About this hypothetical, he states:

“What did the plaintiff lose, or what harm did the lawyer cause the plaintiff, when the lawyer failed to preserve the claim against the insolvent, uninsured driver? The lawyer did not cause the paraplegia, nor did he caused a loss of $50 million, as that money was clearly uncollectible.“

To Justice Crain, the determinative question is the value of the lost judgment.

Insofar as the majority and concurring opinions highlight the absence of any statutes to support their conclusions, it would not be surprising for this issue to be considered by the legislature in coming years.

Collin is a Keogh Cox partner who litigates injury, commercial, and legal malpractice disputes. He lives in nearby Zachary, Louisiana with his wife Melissa and three all too active children. He is an outdoorsman, a tennis player, a cook, and a hobbyist writer.

This blog was written in partnership with Andrew "Drew" Blanchfield whose practice also includes professional liability defense.

Insight

Minimal Force of an Impact Matters in Car Accident Litigation

For years, Louisiana plaintiffs attorneys have argued that the force ofimpact in an auto accident is not determinative of their clients’ injuries andshould be afforded little, if any, weight. A recent decision out of theLouisiana First Circuit Court of Appeal does damage to that argument. In Jonesv. Bravata, Jr. and The City of Baton Rouge, 2018 CA 0837 (La. App. 1 Cir.5/9/19), the First Circuit upheld the trial court's jury instruction on “forceof impact” where photographs showed only minor damage and the defendantdescribed the accident as a “bump.”

The accident occurred when a City employee rear-ended the plaintiffs'vehicle. Liability was stipulated and the only question at trial was damages.Mrs. Jones alleged severe neck and back injuries. She began treatment with anorthopedist within a week of the accident and thereafter received five“relatively non-invasive surgical procedures” in lieu of a lumbar fusionsurgery. The jury returned a verdict of $200,000, which included $150,000 inpast medical expenses and $35,000 in future medical expenses, but awardedlittle for general damages. Mrs. Jones appealed the verdict, asserting that thetrial court erred in instructing the jury on force of impact.

The "force of impact" jury instruction in dispute provided:

Whilethe force of a collision may be considered in determining whether a person wasinjured by an accident and the extent of the injuries sustained, it should notbe the only factor to consider in making such a determination. Even though theforce of impact may be slight, it does not preclude an award of damages.However, in determining causation, you may consider the minimal nature of theaccident.

In considering the plaintiff's assignment of error, the First Circuit noted that Mrs. Jones was correct that no witness specifically testified that the accident was too minor to have caused her injuries. However, there was evidence in the record upon which the jury could have reached the conclusion that this was a minimal impact.

Common sense would appear to support a connection between the force of an impact and the injury one could be expected to suffer. The recent Jones decision allows defendants to promote this common sense argument. Where the claimed injuries are disproportionate to the forces involved, this argument can make the difference at trial.

John Grinton is a partner of the firm admitted in state, federal and appellate courts throughout Louisiana. His practice focuses on commercial and construction litigation, representing insurance companies, architects, engineers, contractors and other businesses in all aspects of litigation. His workers’ compensation practice includes representing clients in medical billing disputes, healthcare provider disputes, statutory/borrowing/special employer disputes, and court approved settlements. John has been involved in complex cases involving construction defect claims, breach of contract and negligence actions, insurance coverage issues, lender liability, securities litigation and personal injury matters. He has firsthand experience in jury trials and arbitration's, as well as mediation, appellate briefing and oral argument.

Richard W. Wolff

Partner
Attorney
Collision
Insurance