Insight

Here Comes Hurricane Ida: What To Do If Your Home is Damaged by a Storm or Flood

Published on: August 28, 2021

Unfortunately, Louisianians have endured many natural disasters in the past several years. From the historic flooding in Baton Rouge in August 2016 to the devastation caused by Hurricanes Laura and Delta in 2020, Gulf Coast residents are very familiar with significant storms and flooding events. While the rebuilding process will take months or years to complete, this article is designed to provide some basic information on how to document and report your property damage claim and apply for and obtain disaster assistance.

  • DOCUMENT, DOCUMENT, DOCUMENT - Once you are able to do so, make sure to document the damages to your home and contents. Whether for a homeowners or flood insurance policy or to obtain government assistance, take plenty of photos of the damage. Make a list of the items in your home that were damaged or destroyed. One way to organize this list is to list each item from each room together, approximate its age, where it was purchased and its value when purchased. As you rebuild, and materials and items are thrown out, it will be much more difficult to document your claim.
  • REPORT YOUR CLAIM – Report your damage to your homeowners or flood insurer as soon as possible. Provide as much detail about the damage as you can. If you are unaware of your insurer, contact your insurance agent who can help you to report your claim.
  • OBTAIN MULTIPLE ESTIMATES - Although it is often difficult to do so after a natural disaster because of the volume of work, obtain multiple estimates for the work needed on your home. Pay for the estimate if necessary. If you have three estimates and the amounts are close, they are much more credible. Also, try and get as much detail as possible in each estimate, including specific materials to be used, dimensions, and finishes.
  • SAVE YOUR RECEIPTS – Whether for repairs you undertake to fix the damage to your home, to replace contents, or for living expenses after the storm, save your receipts. These receipts will be used to document your losses and verify the amount of your claim to your insurer.
  • FOLLOW UP WITH YOUR INSURER - Provide whatever is requested by your insurer as they adjust your claim. Communicate with your insurer on a regular basis. Although it may seem tedious, communication with your insurer during the claim is important.
  • APPLY FOR ASSISTANCE - Especially if your property is not insured, make sure to immediately apply for government assistance. You can apply for federal assistance at www.disasterassistance.gov. Oftentimes, the state government will also administer federal or state disaster assistance funds.

Posted by:

Disclaimer

Keogh Cox & Wilson, Ltd. provides this blog as a public service for general information only. The materials contained herein may not reflect the most current legal developments or even express the opinion of all or even most of Keogh Cox attorneys. Such material does not constitute legal advice or form any attorney-client relationship. Keogh Cox and all contributing author(s) expressly disclaim all liability to any person with respect to the contents of this Web site and Blog and expect that no reliance will be made upon the information provided.

Continue Reading

Explore legal perspectives on the issues shaping Louisiana's key industries and courtrooms.

Insight

Minimal Force of an Impact Matters in Car Accident Litigation

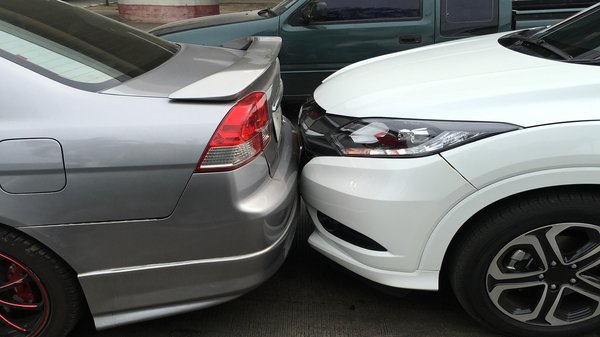
For years, Louisiana plaintiffs attorneys have argued that the force ofimpact in an auto accident is not determinative of their clients’ injuries andshould be afforded little, if any, weight. A recent decision out of theLouisiana First Circuit Court of Appeal does damage to that argument. In Jonesv. Bravata, Jr. and The City of Baton Rouge, 2018 CA 0837 (La. App. 1 Cir.5/9/19), the First Circuit upheld the trial court's jury instruction on “forceof impact” where photographs showed only minor damage and the defendantdescribed the accident as a “bump.”

The accident occurred when a City employee rear-ended the plaintiffs'vehicle. Liability was stipulated and the only question at trial was damages.Mrs. Jones alleged severe neck and back injuries. She began treatment with anorthopedist within a week of the accident and thereafter received five“relatively non-invasive surgical procedures” in lieu of a lumbar fusionsurgery. The jury returned a verdict of $200,000, which included $150,000 inpast medical expenses and $35,000 in future medical expenses, but awardedlittle for general damages. Mrs. Jones appealed the verdict, asserting that thetrial court erred in instructing the jury on force of impact.

The "force of impact" jury instruction in dispute provided:

Whilethe force of a collision may be considered in determining whether a person wasinjured by an accident and the extent of the injuries sustained, it should notbe the only factor to consider in making such a determination. Even though theforce of impact may be slight, it does not preclude an award of damages.However, in determining causation, you may consider the minimal nature of theaccident.

In considering the plaintiff's assignment of error, the First Circuit noted that Mrs. Jones was correct that no witness specifically testified that the accident was too minor to have caused her injuries. However, there was evidence in the record upon which the jury could have reached the conclusion that this was a minimal impact.

Common sense would appear to support a connection between the force of an impact and the injury one could be expected to suffer. The recent Jones decision allows defendants to promote this common sense argument. Where the claimed injuries are disproportionate to the forces involved, this argument can make the difference at trial.

John Grinton is a partner of the firm admitted in state, federal and appellate courts throughout Louisiana. His practice focuses on commercial and construction litigation, representing insurance companies, architects, engineers, contractors and other businesses in all aspects of litigation. His workers’ compensation practice includes representing clients in medical billing disputes, healthcare provider disputes, statutory/borrowing/special employer disputes, and court approved settlements. John has been involved in complex cases involving construction defect claims, breach of contract and negligence actions, insurance coverage issues, lender liability, securities litigation and personal injury matters. He has firsthand experience in jury trials and arbitration's, as well as mediation, appellate briefing and oral argument.

Insight

Limitation of Liability under the LPLA: Can Internet Retailers be Manufacturers?

The Louisiana Products Liability Act (“LPLA”) contains the exclusivetheories of recovery against a manufacturer for damages caused by its product.The term “manufacturer” within the LPLA includes “the seller of a product whoexercises control over or influences a characteristic of the design,construction, or quality of the product that causes damage.” The rapid growthof e-commerce raises a unique question – how do we classify internet retailers?

Internet retailers generally act as a middleman for third partymanufacturers and online consumers. In this respect, they are not technically“sellers” as defined by the LPLA because they typically do not have controlover the design or construction of the products they sell. Nevertheless, theproper categorization of internet retailers may become important when someoneis injured by a product, as was the case in State Farm Fire and CasualtyCompany v. Amazon.com, Inc., 2019 WL 5616708 (Miss. N.D. 10/31/19) ---F.Supp.3d ---.

In State Farm Fire and Casualty Company v. Amazon.com, Inc., two hoverboards purchased through Amazon caught fire inside a Mississippi home and the home was destroyed. In considering Amazon’s possible liability, the Mississippi Court asked whether Amazon was a “service provider” or a “marketplace.” In Mississippi, a finding that Amazon was a “service provider” would insulate it from the claim. However, if Amazon acted as a “marketplace,” it could be exposed by the common law to a negligent failure-to-warn claim. The Mississippi Court held that, because Amazon operated as a marketplace, the claim against it could go forward.

If similar facts arose in Louisiana, could Amazon or similar retailers be exposed under the LPLA? If an internet retailer established policies that forced a “true” manufacturer to negatively alter product quality, would the LPLA provide a remedy? For example, if an internet retailer sets a price ceiling, this artificial figure, especially if unreasonably low, might pressure a manufacturer to lower product safety. Is setting a price range the exercise of enough control or influence over the “design, construction, or quality of a product” to render internet retailers subject to suit under the LPLA? That is a question likely to be answered in cases to come.

Insight

La. Supreme Court Determines Impact of Failure to Pay Filing Fee in Medical Review Panel

The Louisiana Supreme Court recently held that failure to pay filing fees necessary to add a defendant does not invalidate the proceeding as to other defendants. Prior to the ruling, Louisiana courts held that a failure to pay for one defendant invalidated the entire proceeding.

In Kirt v. Metzinger 2019-C-1162 (La. 04/03/20), plaintiffs requested a medical review panel after the death of their mother due to complications after surgery. Plaintiffs named three defendants—two doctors and the hospital. A letter from the Patient’s Compensation Fund Oversight Board (PCF) was mailed to the plaintiffs, confirming that the defendants were qualified under the Louisiana Medical Malpractice Act, and informing the plaintiffs that they were required by La. R.S. 40:1231.8 to pay a filing fee of $100 per named defendant within forty-five days of the mailing of the letter. Plaintiffs responded, requesting to add two additional defendants to the panel, one of whom was an unidentifiable nurse. Plaintiffs also included payment of $500.

The PCF responded that it was unable to add the nurse without proper identification. Three weeks later, plaintiffs notified the PCF they were also unable to identify the nurse. Upon request, Parish Anesthesia was added to the panel instead. Nearly five months later, plaintiffs provided the PCF with the identity of the nurse in question and requested she be added. The PCF sent confirmed the addition and requested another $100 filing fee which was never paid. Nevertheless, the medical review panel thereafter determined that none of the defendants, including the nurse, breached their standard of care. Suit followed against all defendants.

The defendants moved for summary judgment, arguing that the failure to pay the additional filing fee invalidated the proceeding as to all defendants. The trial court granted this motion, and the appellate court affirmed. Reversing the lower courts, the Supreme Court found that the failure to pay the additional $100 filing fee did not invalidate the entire proceeding. The court observed that separate confirmation letters sent by the PCF provided a different forty-five day period during which to pay the filing fee tied to each individual defendant.

The Kirt court stated: “[t]he notion of ‘one filing fee’ for every panel proceeding cannot be reconciled with the different payment deadlines that arise when the PCF sends separate letters confirming defendants’ qualified status. A single filing fee cannot be subject to different payment deadlines.” The court dismissed only the nurse and remanded the remainder of case to the lower courts.

Chad A. Sullivan is a partner with Keogh, Cox & Wilson, Ltd. Prior to becoming an attorney, he worked as a licensed Registered Nurse. He utilizes his background in nursing on a daily basis in his law practice that primarily focuses on automobile liability, medical malpractice, nursing home litigation, healthcare professional licensure and discipline, and products liability.

Christopher K. Jones

Managing Partner
Flood
Louisiana
Hurricane
Insurance